There Is No “Typical” Business Buyer—Which Kind Are You?
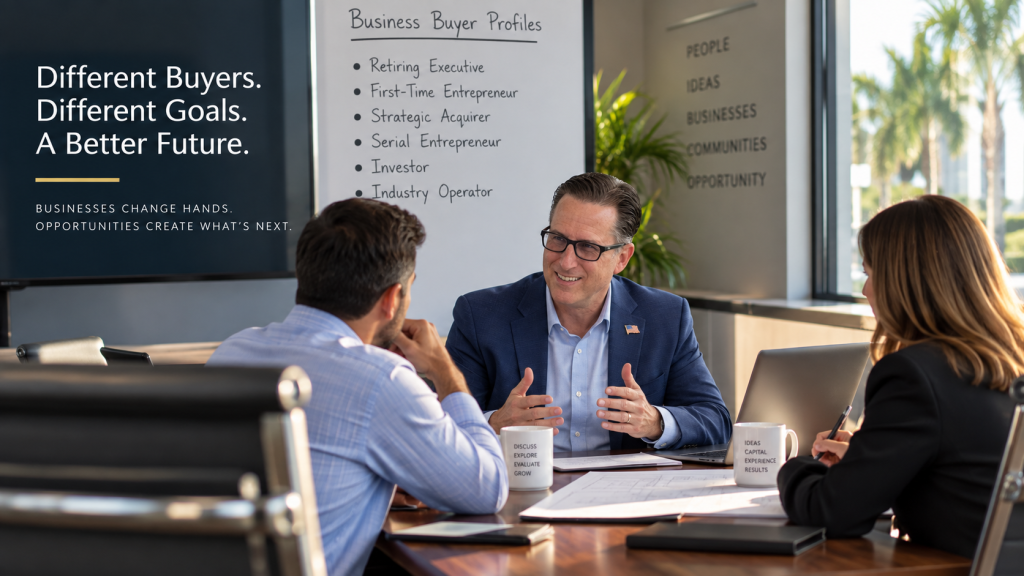
People sometimes talk about “business buyers” as though they’re all looking for the same thing. They’re not. One buyer may be a retiring corporate executive who has spent 30 years building someone else’s company and is finally ready to own one. Another may already own several businesses and be searching for the next acquisition. A successful company may want to acquire a competitor, while an investor may want an established business with management already in place.
All can be legitimate buyers, but they shouldn’t necessarily be looking at the same businesses. That’s why I think one of the first questions a prospective buyer should ask isn’t “What businesses are for sale?” but rather, “What kind of business buyer am I?”
The Executive Ready for Ownership
After 20, 25, or 30 years in corporate America, an executive may have accumulated capital, leadership experience, industry knowledge, and a deep understanding of people, processes, financial performance, and accountability. What they may not have is experience owning the company. That’s an important distinction, but not necessarily a disadvantage.
A seasoned executive may be very well prepared to acquire an established company with employees, customers, systems, and cash flow already in place. Instead of starting from zero, they’re acquiring an operating platform and applying years of experience to something they now own. For this buyer, I pay particular attention to management depth, owner dependency, company culture, employees, existing systems, and how much institutional knowledge currently resides with the seller. The objective isn’t to buy the executive another job; it’s to find a business they can actually lead and own.
The First-Time Entrepreneur
This buyer may be younger, changing careers, coming from a family business, or simply convinced that entrepreneurship is where they want their life to go. Enthusiasm and capital certainly matter, but neither substitutes for fit.
A first-time buyer should think carefully about personal strengths, financial resources, lifestyle expectations, family obligations, leadership ability, risk tolerance, and how involved they want to be in daily operations. Buying an existing company can provide customers, employees, equipment, supplier relationships, operating history, and cash flow from day one, but you’re also inheriting an organization someone else built.
The goal shouldn’t be finding the least expensive business you can afford. It should be finding a business you’re capable of owning successfully.
The Company Growing Through Acquisition
A successful company may determine that acquiring another business is faster or more effective than building the same capabilities organically. The target might bring customers, talented employees, equipment, geographic territory, vendor relationships, recurring revenue, intellectual property, or an entirely new service line. Sometimes the most valuable acquisition isn’t really about acquiring revenue at all—it’s about acquiring capability.
This buyer should be particularly careful with the word synergy. Expected benefits should be identifiable and realistic: shared management, purchasing power, reduced overhead, cross-selling, greater capacity, or expanded market coverage. A strong acquisition should make the combined organization better, but if the numbers only work after assuming every anticipated synergy occurs exactly as planned, I’d want to look much harder at the numbers.
The Serial Entrepreneur, Turnaround Buyer, or Investor
Some entrepreneurs genuinely enjoy improving businesses more than maintaining them. They look at an underperforming company and immediately see opportunities involving pricing, marketing, technology, staffing, leadership, customer experience, purchasing, or operating systems. This buyer isn’t necessarily searching for perfection because perfection may leave very little opportunity to create additional value.
One principle I particularly like is: Don’t simply buy someone else’s problems. Buy problems you know how to solve. A fundamentally sound company with weak marketing may be an outstanding opportunity for someone who understands customer acquisition. A company with poor systems may appeal to an experienced operator, while an owner-dependent business may interest someone capable of building a stronger management structure.
There is also the investor who wants business ownership without acquiring another full-time job. For that buyer, management depth becomes critical. Who actually runs the company? Who owns the customer relationships? Are processes documented? Can the business operate effectively without the seller? A profitable company that depends entirely upon its current owner may be a poor passive investment, while one supported by capable people and repeatable systems may represent something very different.
Start With the Buyer—Then Search for the Business
This is where I think many acquisition searches get backward. Someone decides they want to buy a business, begins scrolling through listings, and then tries to determine whether one of those businesses fits.
I’d rather begin by developing the buyer profile. What experience do you bring? How much capital are you prepared to invest? What income does the business need to produce? How will it be financed? Which industries make sense? How geographically flexible are you? How involved do you want to be? Are you looking for stability, growth, turnaround potential, or a strategic acquisition?
Once we understand those answers, the search becomes considerably more focused.
If you’re beginning to recognize yourself in one of these buyer profiles…
We don’t need to start by looking at listings. We can begin by defining what a successful acquisition would actually look like for you, then determine which opportunities deserve your time and capital.
On-Market Isn’t the Entire Market
I have access to a wide variety of businesses currently being offered for sale through the marketplace and the broader resources and relationships available through CIBB/CRE. For the right qualified buyer, however, an acquisition search doesn’t necessarily have to stop with publicly marketed opportunities.
Once we have a clearly defined acquisition profile, we can also consider identifying businesses that fit the criteria and approaching owners who may be receptive to a confidential conversation even though their companies aren’t publicly advertised for sale. That doesn’t mean every off-market owner wants to sell. It means a thoughtful acquisition search can sometimes extend beyond simply asking, “What’s listed today?”
The better question is: “Where are the businesses that fit what we’re actually trying to accomplish?”
The Same Business Can Mean Something Different to Every Buyer
Imagine the same profitable company being evaluated by five buyers. The first-time entrepreneur sees independence and an established source of income. The retiring executive sees the next chapter of a career. A competitor sees customers, employees, and market share. A serial entrepreneur sees operational improvements capable of creating additional value. An investor sees a management team and systems capable of producing income without requiring daily involvement.
Same company. Five different investment theses.
That’s why a profitable, growing, well-managed, fairly priced company can still be the wrong acquisition for a particular buyer. Your capital, experience, leadership style, desired involvement, financing, risk tolerance, family circumstances, and long-term goals all matter. A sophisticated buyer eventually learns the difference between a good opportunity and the right opportunity.
And sometimes the right decision is not to buy at all. There will be another business. Capital and time deserve to be protected until an opportunity truly makes sense.
What Kind of Business Buyer Are You?
Maybe you’re preparing to leave corporate life. Perhaps you’re an entrepreneur looking for your first acquisition, an established company ready to grow through acquisition, or an experienced buyer who already knows exactly what you’re looking for.
That’s where I can help. I bring the perspective of someone who spent decades leading businesses and 16 years owning and operating one myself, together with the business brokerage resources, market knowledge, and opportunities available through CIBB/CRE. We can begin by defining who you are as a buyer, what you’re trying to accomplish, and what a successful acquisition would actually look like for you.
Then we go looking—not simply for a business that’s for sale, but for a business worth buying.